Disclaimer
All information shown on this page is for illustrative purposes only and should not be construed as investment, financial, market or other advice. Any information shown on this page that purports to be based upon past or current market conditions may not be complete, timely or accurate and, in any event, is not predictive of future outcomes.
Report This Indicator
(Options Conviction Score)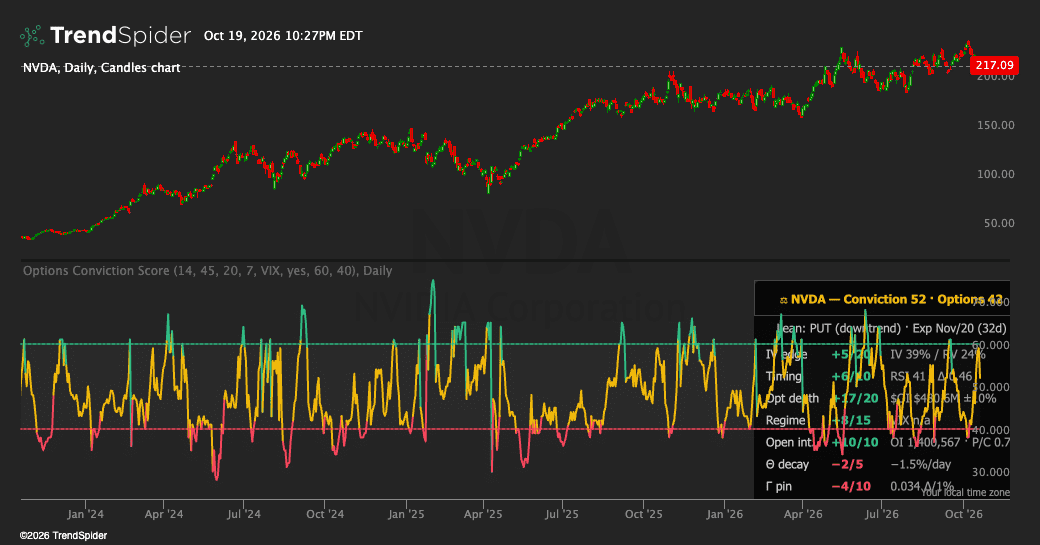
Options Conviction Score — a 0–100 composite answering two questions: Is this a favorable setup for buying options right now, and which side offers the better opportunity?
The underlying score evaluates the stock’s setup on every bar, combining contrarian dip quality, RSI timing, liquidity, VIX regime, and dollar-volume growth, with a chaos penalty for falling-knife price action. Green ≥60, amber 40–59, red
TSBuild26
/**
 * Options Conviction Score — TrendSpider Custom Indicator
 * ========================================================
 *
 * "Is this a good time to BUY premium on this underlier — and which side?"
 *
 * Two readouts sharing one factor model (ported from an autonomous trading
 * agent's conviction engine — see docs):
 *
 *   1. CONVICTION LINE (per bar, 0–100) — the underlier's setup score, an
 *      equity port of the 6-factor contrarian engine:
 *        contrarian 30 · RSI timing 10 · quality 20 · regime 20 ·
 *        volume growth 10 · − vol-path penalty 15
 *      It needs only OHLCV (+ optional VIX history), so it paints history.
 *
 *   2. OPTIONS EDGE PANEL (live OPRA snapshot) — the full 8-factor options
 *      model evaluated on a target expiry:
 *        IV contrarian 20 · RSI+delta 10 · options depth 20 · VIX regime 15 ·
 *        open interest 10 · − theta decay 5 · − gamma pin 10 · ± earnings 10
 *
 * Zones: ≥60 (green) historically favorable premium-buying conditions,
 * 40–60 neutral, ≤40 avoid. Contrarian by design — deep-but-orderly weakness
 * scores high; chasing strength scores low.
 *
 * Notes:
 *  - Options panel requires an OPRA data subscription; on tickers without
 *    options (or without the add-on) the line still works and the panel
 *    reports "no options chain".
 *  - Daily chart recommended. Other resolutions work; RV annualization
 *    auto-scales (252 trading days, 390-min session).
 *  - paint() call count is constant per run (TrendSpider rule): hidden
 *    series are painted via constants.empty_series where needed.
 */

describe_indicator('Options Conviction Score', 'lower');

// ────────────────────────────── Inputs ──────────────────────────────────────

const minDte       = input.number('Min DTE',        14, { min: 0, max: 180 });
const maxDte       = input.number('Max DTE',        45, { min: 1, max: 365 });
const rvLen        = input.number('RV Lookback',    20, { min: 5, max: 120 });
const earnWindow   = input.number('Earnings Window (d)', 7, { min: 1, max: 30 });
const vixSymbol    = input.symbol('VIX symbol',     'VIX');
const showPanel    = input.boolean('Show options panel', true);
const buyZone      = input.number('Favorable zone ≥',   60, { min: 1, max: 99 });
const avoidZone    = input.number('Avoid zone ≤',       40, { min: 0, max: 98 });
const greenColor   = '#2ebd85';
const amberColor   = '#f0b90b';
const redColor     = '#f6465d';

// ───────────────────────── Factor helpers (ported) ──────────────────────────

const clamp01 = (x) => Math.max(0, Math.min(1, x));

/** Contrarian fraction: the "early" sweet spot is −15%…−50% over 7 bars.
 *  Chasing strength scores ~0; capitulation past −70% scores 0.15, not 0. */
function contrarianFraction(pct7) {
    const floor = -70;
    if (pct7 <= floor) return 0.15;
    if (pct7 <= -50) return 0.15 + ((pct7 - floor) / (-50 - floor)) * 0.85;
    if (pct7 <= -15) return 1.0;
    if (pct7 < 0)    return 0.4 + ((-pct7) / 15) * 0.6;
    if (pct7 <= 25)  return Math.max(0, 0.4 * (1 - pct7 / 25));
    return 0;
}

/** RSI timing fraction (calls side — oversold is good timing). */
function rsiTimingFraction(r) {
    if (r == null) return 0.5;
    if (r <= 25) return 1.0;
    if (r <= 35) return 0.85;
    if (r <= 50) return 0.5;
    if (r <= 65) return 0.25;
    return 0;
}

/** Vol-path penalty: how far the last bar deviates from the smooth 7-bar
 *  drift. A smooth dip scores 0 (that's the "early" trade); a choppy,
 *  bouncing path is a falling knife — penalized. Max at 20pp deviation. */
function volPenaltyFraction(pct7, pct1) {
    return clamp01(Math.abs(pct1 - pct7 / 7) / 20);
}

/** Equity quality: 20-bar dollar volume + underlier price scale
 *  (mega-caps have institutionally deep option markets by construction). */
function equityQualityFraction(avgDollarVol, price) {
    const v = avgDollarVol ?? 0;
    let frac = 0.1;
    if (v >= 5e8) frac = 1.0;
    else if (v >= 1e8) frac = 0.85;
    else if (v >= 2.5e7) frac = 0.7;
    else if (v >= 5e6) frac = 0.5;
    else if (v >= 1e6) frac = 0.3;
    const priceFrac = price >= 200 ? 1.0 : price >= 100 ? 0.75 : price >= 50 ? 0.5 : 0.25;
    return Math.max(frac, priceFrac * 0.6);
}

/** Volume-growth fraction (equity stand-in for on-chain holder growth):
 *  growth % of 20-bar vs 60-bar average dollar volume. */
function volumeGrowthFraction(growthPct) {
    const g = growthPct;
    if (g == null || !isFinite(g)) return 0.4;
    if (g <= -5) return 0;
    if (g <= 0)  return 0.4 * (1 + g / 5);
    if (g <= 10) return 0.4 + (g / 10) * 0.6;
    return 1.0;
}

/** VIX regime fraction — fear is the contrarian's opportunity. */
function vixFraction(vix) {
    if (vix == null || !isFinite(vix)) return 0.5;
    if (vix >= 35) return 1.0;
    if (vix >= 25) return 0.7;
    if (vix >= 15) return 0.5;
    return 0.3;
}

/** IV contrarian fraction, premium-BUYER perspective. IV/RV < 1 = premium
 *  cheaper than the underlier's own realized vol → buy edge. Rich IV/RV is
 *  crush-prone → avoid. Degenerate IV (<5% annualized) is a stale quote,
 *  not "cheap" — neutral. */
function ivContrarianFraction(iv, ivToRv) {
    if (iv == null || iv <= 0 || iv < 0.05) return 0.5;
    if (ivToRv > 0) {
        if (ivToRv >= 2.0) return 0.1;
        if (ivToRv >= 1.4) return 0.25;
        if (ivToRv >= 1.1) return 0.4;
        if (ivToRv >= 0.9) return 0.5;
        if (ivToRv >= 0.6) return 0.7;
        if (ivToRv >= 0.4) return 0.9;
        return 1.0;
    }
    if (iv >= 1.0) return 0.1;
    if (iv >= 0.6) return 0.25;
    if (iv >= 0.3) return 0.5;
    if (iv >= 0.15) return 0.75;
    return 0.5;
}

/** Delta quality — reward 0.25–0.55 (a real option), penalize lotto tickets
 *  and stock substitutes. */
function deltaQualityFraction(absDelta) {
    if (absDelta < 0.15) return 0.1;
    if (absDelta < 0.25) return 0.35;
    if (absDelta <= 0.55) return 1.0;
    if (absDelta <= 0.7) return 0.55;
    return 0.25;
}

/** Theta decay fraction (penalty) on decay-per-day as % of premium. */
function thetaDecayFraction(thetaPct) {
    if (thetaPct == null) return 0.4;
    if (thetaPct >= 0.08) return 1.0;
    if (thetaPct >= 0.03) return 0.7;
    if (thetaPct >= 0.012) return 0.4;
    return 0.1;
}

/** Gamma squeeze/pin fraction (penalty) on normalized gamma:
 *  Δdelta points per 1% underlier move (gamma × spot / 100).
 *  Typical ATM: ~0.03 for a 45d expiry, ~0.06 for 14d, ≥0.15 near-dated. */
function gammaPinFraction(gammaPerPct) {
    if (gammaPerPct == null) return 0.4;
    if (gammaPerPct >= 0.15) return 1.0;
    if (gammaPerPct >= 0.07) return 0.7;
    if (gammaPerPct >= 0.03) return 0.4;
    return 0.1;
}

/** Open-interest fraction (depth/activity proxy). */
function oiFraction(totalOi) {
    if (totalOi >= 10000) return 1.0;
    if (totalOi >= 1000) return 0.6;
    if (totalOi >= 100) return 0.3;
    return 0.1;
}

// ─────────────────────── Chart-native per-bar scoring ───────────────────────

const n = close.length;
const rsi14 = rsi(close, 14);
const sma50 = sma(close, 50);

const dvol = series_of(null);
for (let i = 0; i < n; i++) dvol[i] = (close[i] ?? 0) * (volume[i] ?? 0);
const dvol20 = sma(dvol, 20);
const dvol60 = sma(dvol, 60);

// VIX history (optional — regime factor degrades to neutral without it).
let vixLanded = series_of(null);
try {
    if (vixSymbol) {
        const vixData = await request.history(vixSymbol, current.resolution);
        if (vixData && !vixData.error && vixData.time && vixData.time.length) {
            vixLanded = interpolate_sparse_series(
                land_points_onto_series(vixData.time, vixData.close, time),
                'constant'
            );
        }
    }
} catch (e) { vixLanded = series_of(null); }

const conviction = series_of(null);
for (let i = 0; i < n; i++) {
    if (i < 61) continue;                       // need 60-bar vol + 50 SMA
    const r7 = (close[i] / close[i - 7] - 1) * 100;
    const r1 = (close[i] / close[i - 1] - 1) * 100;
    const growthPct = dvol60[i] > 0 ? (dvol20[i] / dvol60[i] - 1) * 100 : null;
    const score =
        contrarianFraction(r7)          * 30 +
        rsiTimingFraction(rsi14[i])     * 10 +
        equityQualityFraction(dvol20[i], close[i]) * 20 +
        vixFraction(vixLanded[i])       * 20 +
        volumeGrowthFraction(growthPct) * 10 -
        volPenaltyFraction(r7, r1)      * 15;
    conviction[i] = Math.round(Math.max(0, Math.min(100, score)));
}

// ─────────────────── Live options surface (OPRA snapshot) ───────────────────

// Periods/year for RV annualization — daily default; intraday ≈ 390-min
// sessions; weekly/monthly mapped.
const resNum = Number(constants.resolution);
const periodsPerYear = Number.isFinite(resNum)
    ? Math.round(252 * 390 / resNum)
    : ({ D: 252, W: 52, M: 12 }[constants.resolution] ?? 252);

function realizedVol(klines, lookback, ppy) {
    const m = klines.length;
    if (m < lookback + 1) return null;
    const rets = [];
    for (let i = m - lookback; i < m; i++) {
        if (klines[i - 1] > 0 && klines[i] > 0) rets.push(Math.log(klines[i] / klines[i - 1]));
    }
    if (rets.length < 2) return null;
    const mean = rets.reduce((a, b) => a + b, 0) / rets.length;
    const varSum = rets.reduce((a, r) => a + (r - mean) * (r - mean), 0) / (rets.length - 1);
    return Math.sqrt(varSum) * Math.sqrt(ppy);
}

const mid = (q) => {
    if (!q) return null;
    if (q.l && q.l > 0) return q.l;
    if (q.b > 0 && q.a > 0) return (q.b + q.a) / 2;
    if (q.b > 0) return q.b;
    if (q.a > 0) return q.a;
    return null;
};

let opt = null;
try {
    const schedule = await request.options_schedule(current.ticker);
    if (schedule && !schedule.error && schedule.length) {
        const inRange = schedule.filter(e =>
            e?.expiration?.dte != null && e.expiration.dte >= minDte && e.expiration.dte <= maxDte
        );
        const pick = inRange.find(e => e.expiration.schedule === 'M') ?? inRange[0];
        if (pick) {
            const chain = await request.options_data_for_expiration(
                current.ticker,
                pick.expiration.code.toString(),
                ['l', 'b', 'a', 'iv', 'oi', 'gd', 'gg', 'gt', 'dvol']
            );
            if (chain && !chain.error && chain.resultByStrike) {
                const spot = chain.underlyingSymbolQuote?.lastPrice ?? close[n - 1];
                const strikes = Object.keys(chain.resultByStrike).map(Number).sort((a, b) => a - b);
                if (strikes.length) {
                    // ATM bracket interpolation (same method as the reference impl)
                    let lo = 0;
                    for (let i = 0; i < strikes.length; i++) {
                        if (strikes[i] <= spot) lo = i; else break;
                    }
                    const hi = Math.min(lo + 1, strikes.length - 1);
                    const kLo = strikes[lo], kHi = strikes[hi];
                    const t = kHi !== kLo ? (spot - kLo) / (kHi - kLo) : 0;
                    const lerp = (a, b) => (a != null && b != null) ? a + t * (b - a) : (a ?? b);

                    // Directional lean: trend vs 50-bar SMA picks the side.
                    const trendUp = close[n - 1] >= (sma50[n - 1] ?? close[n - 1]);
                    const side = trendUp ? 'C' : 'P';
                    const dLo = chain.resultByStrike[kLo], dHi = chain.resultByStrike[kHi];
                    const sLo = dLo?.[side], sHi = dHi?.[side];

                    // OPRA 'iv' arrives percent-scale (39.16 = 39.16% IV);
                    // normalize to decimal like the delta field below.
                    const rawIv     = lerp(dLo?.C?.iv ?? dLo?.P?.iv, dHi?.C?.iv ?? dHi?.P?.iv);
                    const atmIv     = rawIv != null && rawIv > 5 ? rawIv / 100 : rawIv;
                    const atmDelta  = Math.abs(lerp(sLo?.gd, sHi?.gd) ?? 0.5);
                    const normDelta = atmDelta > 1 ? atmDelta / 100 : atmDelta;
                    const atmMid    = lerp(mid(sLo), mid(sHi));
                    const atmTheta  = lerp(sLo?.gt, sHi?.gt);
                    const atmGamma  = Math.max(lerp(dLo?.C?.gg ?? 0, dHi?.C?.gg ?? 0) ?? 0,
                                               lerp(dLo?.P?.gg ?? 0, dHi?.P?.gg ?? 0) ?? 0);

                    // Surface totals across the whole expiry.
                    let callOi = 0, putOi = 0, dollarOi = 0;
                    for (const k of strikes) {
                        const d = chain.resultByStrike[k];
                        callOi += d?.C?.oi ?? 0;
                        putOi  += d?.P?.oi ?? 0;
                        if (Math.abs(k / spot - 1) <= 0.10) {
                            const cMid = mid(d?.C), pMid = mid(d?.P);
                            dollarOi += ((cMid ?? 0) * (d?.C?.oi ?? 0) +
                                         (pMid ?? 0) * (d?.P?.oi ?? 0)) * 100;
                        }
                    }
                    const totalOi = callOi + putOi;
                    const pcOi = callOi > 0 ? putOi / callOi : null;

                    const rv = realizedVol(close, rvLen, periodsPerYear);
                    const ivToRv = (atmIv > 0 && rv > 0) ? atmIv / rv : 0;
                    const thetaPct = (atmTheta != null && atmMid > 0) ? Math.abs(atmTheta) / atmMid : null;
                    const gammaPerPct = spot > 0 ? (atmGamma * spot) / 100 : null;

                    opt = {
                        score: null,
                        spot, dte: pick.expiration.dte, expiry: pick.expiration,
                        atmIv, ivToRv, rv, atmDelta: normDelta, atmMid,
                        callOi, putOi, totalOi, pcOi, dollarOi,
                        thetaPct, gammaPerPct, side, trendUp,
                    };
                }
            }
        }
    }
} catch (e) { opt = null; }

// Next earnings (vol-crush timing). request.earnings returns {timestamp,…}
// in seconds; the nearest future record is the risk window.
let earnDays = null;
try {
    const earnings = await request.earnings(current.ticker);
    if (Array.isArray(earnings) && earnings.length) {
        const nowSec = Math.max(Date.now() / 1000, time[n - 1] ?? 0);
        const future = earnings
            .map(e => e.timestamp)
            .filter(ts => ts != null && ts > nowSec)
            .sort((a, b) => a - b);
        if (future.length) earnDays = Math.round((future[0] - nowSec) / 86400);
    }
} catch (e) { earnDays = null; }

// ─────────────────────── Options conviction (8 factors) ─────────────────────

if (opt) {
    const rsiNow = rsi14[n - 1];
    const rsiT = rsiTimingFraction(opt.side === 'C' ? rsiNow : (rsiNow == null ? null : 100 - rsiNow));
    const f = {
        iv:      { pts: ivContrarianFraction(opt.atmIv, opt.ivToRv) * 20, max: 20,
                   detail: opt.atmIv != null
                       ? `IV ${(opt.atmIv * 100).toFixed(0)}% / RV ${opt.rv ? (opt.rv * 100).toFixed(0) + '%' : 'n/a'}`
                       : 'IV n/a' },
        timing:  { pts: (rsiT * 0.6 + deltaQualityFraction(opt.atmDelta) * 0.4) * 10, max: 10,
                   detail: `RSI ${rsiNow == null ? 'n/a' : Math.round(rsiNow)} · Δ ${opt.atmDelta.toFixed(2)}` },
        depth:   { pts: equityQualityFraction(opt.dollarOi, opt.spot) * 20, max: 20,
                   detail: `$OI $${opt.dollarOi >= 1e6 ? (opt.dollarOi / 1e6).toFixed(1) + 'M' : Math.round(opt.dollarOi / 1e3) + 'k'} ±10%` },
        regime:  { pts: vixFraction(vixLanded[n - 1]) * 15, max: 15,
                   detail: vixLanded[n - 1] != null ? `VIX ${vixLanded[n - 1].toFixed(1)}` : 'VIX n/a' },
        oi:      { pts: oiFraction(opt.totalOi) * 10, max: 10,
                   detail: `OI ${opt.totalOi.toLocaleString()} · P/C ${opt.pcOi != null ? opt.pcOi.toFixed(2) : 'n/a'}` },
        theta:   { pts: -thetaDecayFraction(opt.thetaPct) * 5, max: 5,
                   detail: opt.thetaPct != null ? `−${(opt.thetaPct * 100).toFixed(1)}%/day` : 'n/a' },
        gamma:   { pts: -gammaPinFraction(opt.gammaPerPct) * 10, max: 10,
                   detail: opt.gammaPerPct != null ? `${opt.gammaPerPct.toFixed(3)} Δ/1%` : 'n/a' },
        earn:    { pts: (earnDays != null && earnDays <= earnWindow) ? -10 : 3, max: 10,
                   detail: earnDays != null ? `in ${earnDays}d` : 'none ahead' },
    };
    const raw = Object.values(f).reduce((s, x) => s + x.pts, 0);
    opt.score = Math.round(Math.max(0, Math.min(100, raw)));
    opt.factors = f;
}

// ─────────────────────────────── Paints ─────────────────────────────────────
// Constant paint() count per run (platform rule).

const zoneColors = for_every(conviction, s =>
    s == null ? null : s >= buyZone ? greenColor : s > avoidZone ? amberColor : redColor
);

paint(conviction, {
    name: 'Conviction',
    color: zoneColors,
    style: 'line',
    thickness: 2,
});

const gFav = paint(horizontal_line(buyZone), {
    name: 'Favorable ≥',
    color: series_of(greenColor),
    style: 'dotted',
    ignoreWhenScaling: true,
});
const gAvoid = paint(horizontal_line(avoidZone), {
    name: 'Avoid ≤',
    color: series_of(redColor),
    style: 'dotted',
    ignoreWhenScaling: true,
});
fill(gFav, gAvoid, '#888888', 0.05);

// Zone-cross markers removed — the zone-colored line + threshold guides
// already communicate crossings; bubbles rendered oversized on the 0–100
// pane at every tested z-scale and cluttered the view.

// ────────────────────────────── Overlay panel ───────────────────────────────

const convNow = conviction[n - 1];
const scoreColor = (s) => s == null ? '#888' : s >= buyZone ? greenColor : s > avoidZone ? amberColor : redColor;
const fmtPts = (p) => (p >= 0 ? '+' : '−') + Math.abs(Math.round(p));

const rows = [];
rows.push({ cells: [{
    colspan: 3,
    text: `⚖ ${current.ticker} — Conviction ${convNow ?? 'n/a'}` +
          (opt?.score != null ? ` · Options ${opt.score}` : ''),
    fontWeight: 'bold',
    color: opt?.score != null ? scoreColor(opt.score) : scoreColor(convNow),
    textAlign: 'center',
    padding: '8px 12px',
    border: '1px solid #444',
}]});

if (opt) {
    const lean = opt.trendUp
        ? (rsi14[n - 1] != null && rsi14[n - 1] <= 45 ? 'CALL (dip in uptrend)' : 'CALL (uptrend)')
        : (rsi14[n - 1] != null && rsi14[n - 1] >= 60 ? 'PUT (rally in downtrend)' : 'PUT (downtrend)');
    const expLabel = [opt.expiry?.month, opt.expiry?.day].filter(x => x != null).join('/');
    rows.push({ cells: [{
        colspan: 3,
        text: `Lean: ${lean} · Exp ${expLabel || '?'} (${opt.dte}d)`,
        color: '#bbb', textAlign: 'center', padding: '2px 12px 6px',
    }]});

    const order = [
        ['iv',    'IV edge'],
        ['timing','Timing'],
        ['depth', 'Opt depth'],
        ['regime','Regime'],
        ['oi',    'Open int.'],
        ['theta', 'Θ decay'],
        ['gamma', 'Γ pin'],
        ['earn',  'Earnings'],
    ];
    for (const [key, label] of order) {
        const x = opt.factors[key];
        rows.push({ cells: [
            { text: label, color: '#ccc', padding: '2px 6px 2px 12px' },
            { text: `${fmtPts(x.pts)}/${x.max}`, color: x.pts >= 0 ? greenColor : redColor,
              fontWeight: 'bold', padding: '2px 6px' },
            { text: x.detail, color: '#999', padding: '2px 12px 2px 6px' },
        ]});
    }
} else {
    rows.push({ cells: [{
        colspan: 3,
        text: 'No options chain on this ticker (or OPRA add-on inactive)',
        color: '#888', textAlign: 'center', padding: '2px 12px 8px',
    }]});
}

paint_overlay('OptionsConviction', { position: 'top_right', offset_x: 20, offset_y: 20 }, {
    fontSize: 12,
    background: '#000000cc',
    borderRadius: '8px',
    rows,
    hidden: !showPanel,
});
Traders also viewed